
Did you know that Florida’s foreclosure filings in the first half of 2026 jumped by approximately 33% compared to the previous year? If you’re facing this situation, you aren’t alone, but you’re likely worried about your hard-earned equity. It’s natural to feel overwhelmed by lender pressure and strict judicial timelines. You might find yourself staring at a tax assessment and wondering if it reflects the true property value in foreclosure Florida homeowners actually need to know. Most people assume the bank’s valuation is the final word, but that’s rarely the case.
You deserve a clear, data-driven path forward. This guide will show you exactly how property value is determined during the Florida foreclosure process and how to protect your financial future with professional appraisal insights. We’ll break down the differences between market value and liquidation value, explain the 120-day delinquency rule, and show you how to use an accurate valuation to negotiate a short sale or refinance. Detailed. Objective. Decisive. By the end of this article, you’ll have the professional data needed to regain control and find peace of mind.
Key Takeaways
- Learn the critical difference between Fair Market Value and Liquidation Value to understand how lenders assess your home’s worth during a crisis.
- Discover why determining the accurate property value in foreclosure Florida is essential for protecting your remaining equity during the judicial process.
- Identify how specific factors, such as deferred maintenance and local neighborhood trends, can significantly impact a distressed property appraisal.
- Use a private pre-foreclosure appraisal to establish a “defense value” for more effective short sale negotiations and court-ordered mediation.
- Gain the professional clarity needed to decide whether to sell, refinance, or pursue a legal defense based on objective valuation data.
Understanding Property Value in Foreclosure Florida
In the context of a legal crisis, property value isn’t a fixed target. It is a moving data point influenced by court proceedings and market shifts. Determining the property value in foreclosure Florida homeowners rely on requires looking beyond standard real estate listings to understand how the law views your home’s worth. This valuation serves as the foundation for every decision you make, from negotiating a short sale to defending your equity in court.
The Impact of Judicial Foreclosure on Valuation
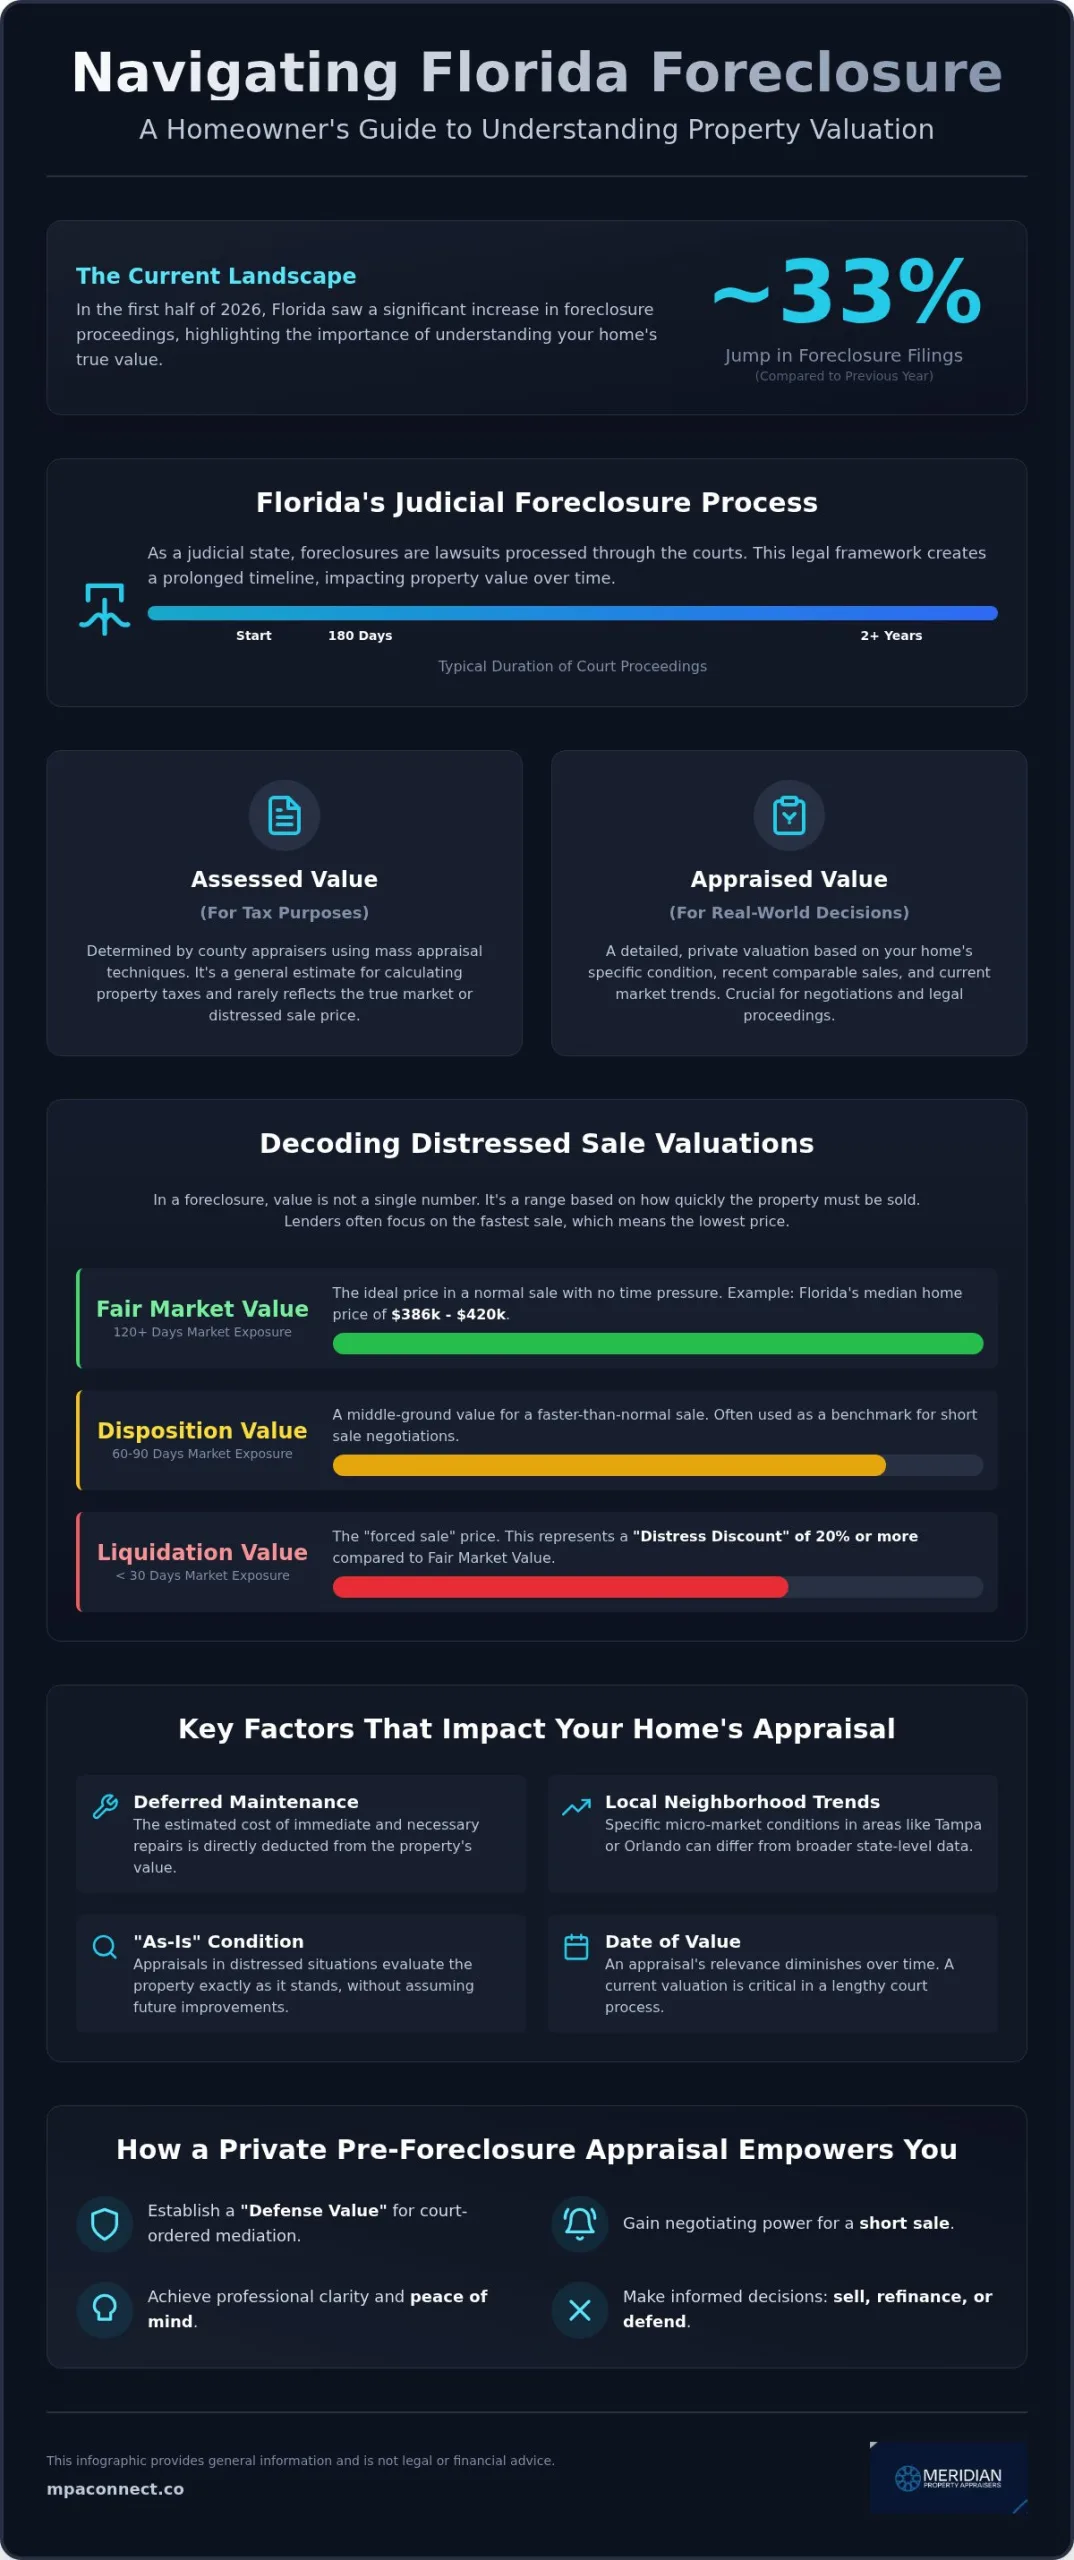
Florida operates as a judicial foreclosure state. This means every step of the process happens under court supervision, requiring a lender to file a lawsuit to regain the property. Understanding the Foreclosure Process within this legal framework is vital because the timeline often stretches from 180 days to over two years. During this period, your equity isn’t static. In the 2026 market, where Florida saw a modest 2.8% year-over-year appreciation in June, a long legal delay might actually help some homeowners build equity. Conversely, if the market dips or the property falls into disrepair, those same months can erode your financial cushion.
The “Date of Value” is a critical factor in these proceedings. An appraisal conducted at the start of a lawsuit might be irrelevant by the time a final judgment is issued. Precise. Objective. Defensible. These are the qualities your data must have to stand up in a 2026 Florida courtroom. Professional valuations account for these temporal shifts, ensuring you aren’t relying on outdated figures when your financial future is on the line.
Assessed Value vs. Appraised Value
Many homeowners rely on their annual TRIM notice to estimate their home’s worth. This is a common mistake. The county appraiser’s office uses mass appraisal techniques designed for taxation, not for individual sales or legal settlements. There is often a significant gap between government data and a private certified appraisal that accounts for your home’s specific condition and unique neighborhood trends in hubs like Tampa, Saint Petersburg, and Orlando. As explored in our guide on inherited property appraisal in Tampa, relying on a county tax assessment instead of a professional valuation can lead to serious financial and legal consequences.
Just Value is defined by Florida county appraisers as the full, fair, and objective market value of a property as of January 1st of each year, minus the costs of sale. While this number is useful for tax purposes, it rarely reflects what a buyer would pay in a distressed sale environment. A private pre-foreclosure appraisal provides a more current, granular view of the property value in foreclosure Florida residents need to negotiate effectively with lenders. This distinction ensures you have an accurate baseline for mediation rather than a generic government estimate. Homeowners in the Tampa Bay region can learn more about how private certified valuations differ from county records in our overview of working with a certified home appraiser St Petersburg FL residents trust for legally defensible results.
Fair Market Value vs. Liquidation Value in Distressed Sales
In a typical real estate transaction, Fair Market Value (FMV) assumes both the buyer and seller are acting prudently, without pressure, and with a reasonable amount of time for the property to be exposed to the market. In mid-2026, Florida’s median home price ranges from $386,333 to $420,000, figures that generally reflect FMV. However, as the Florida Foreclosure Process moves into the judicial phase, the definition of value shifts toward urgency. This transition introduces Liquidation Value, the price a property would likely bring in a forced sale with an extremely limited marketing window.
Lenders prioritize Liquidation Value because it represents a worst-case scenario for debt recovery. Between these two extremes lies Disposition Value, which serves as a middle ground. This figure assumes a shortened marketing period, usually 60 to 90 days, and is frequently the benchmark used during short sale negotiations. The “As-Is” condition of the home drastically influences these tiers. When maintenance is deferred due to financial strain, the property value in foreclosure Florida homeowners expect can drop significantly, as appraisers must deduct the costs of immediate repairs from the final number.
Tiered Valuation Methods for Florida Homes
Certified appraisal reports for distressed properties often categorize value based on exposure time. A standard appraisal might assume 120 days or more of market exposure. In contrast, a liquidation assessment might assume fewer than 30 days. Forced sale conditions often result in a “distress discount” that can lower the valuation by 20% or more compared to a traditional sale. Identifying which tier applies to your situation is the first step in protecting your equity. Obtaining a Pre-Foreclosure Appraisal allows you to see these tiers clearly before you enter mediation with a lender.
Why the Bank’s Appraisal Might Be Lower
Banks frequently rely on Broker Price Opinions (BPOs) instead of comprehensive certified appraisals. BPOs are often conducted by real estate agents who may not have the same level of rigorous training in valuation methodology as a certified appraiser. These assessments are sometimes “drive-by” inspections, meaning the evaluator never steps inside to see the home’s true condition.
Common errors in bank-led valuations include using inappropriate “comps” or failing to adjust for the unique judicial timelines inherent to Florida law. A private appraiser provides a more thorough, ethical assessment. By conducting a full interior and exterior inspection, an independent professional ensures that the property value in foreclosure Florida courts see is based on granular data rather than a lender’s internal recovery targets. This methodical approach provides the peace of mind that your home’s worth is being calculated with integrity and precision.
Key Factors That Influence Your Home’s Foreclosure Appraisal
Physical condition acts as a primary lever for the property value in foreclosure Florida homeowners must monitor. When financial pressure mounts, deferred maintenance often follows. A leaky roof or a failing HVAC system doesn’t just cost the price of the repair; it triggers a steep “distress discount” from potential investors who factor in the risk of unknown defects. For South Florida residents, addressing aesthetic issues can be a simple way to improve appeal; learn more about how Florida Painting LLC provides professional painting services that can help restore your property’s appearance. Beyond the home’s walls, neighborhood trends play a massive role. In the first half of 2026, Florida had the highest foreclosure rate in the nation, with one in every 373 homes in some stage of the process. This saturation can drag down the value of even well-maintained properties by creating a surplus of distressed inventory in your immediate area.
Florida-specific variables, such as flood zones and hurricane readiness, add another layer of scrutiny. Homes that do not meet modern hurricane standards or those subject to strict FEMA rules regarding substantial improvement face unique valuation hurdles. If a home requires significant updates to meet current codes, those costs are deducted from the final appraisal. This further impacts the equity you’re trying to protect, making hurricane-rated windows and updated roofing essential data points for a fair assessment.
Internal vs. External Obsolescence
Internal obsolescence occurs when a home’s layout or lack of modern upgrades makes it less desirable than non-distressed neighbors. External factors are equally impactful. In 2026, with the 30-year fixed mortgage rate hovering around 6.75%, the pool of qualified buyers has shrunk. This reduced demand is particularly visible in high-growth hubs like Tampa, Orlando, and St. Petersburg, where inventory has increased. When fewer buyers are competing, the property value in foreclosure Florida residents experience is often dictated by the most aggressive cash offers rather than emotional retail buyers.
The Role of Comparable Sales (Comps)
Traditional “comps”-sales of similar homes in the last six months-may not accurately reflect a distressed market state. A professional appraiser must look for other distressed sales or short sales to establish a realistic baseline. An appraiser adjusts for a distressed sale by applying a percentage-based discount to reflect the limited marketing time and the perceived risk associated with a non-traditional purchase. This methodical adjustment ensures the data is relevant to the judicial context rather than a hypothetical market scenario where everything is perfect.
Why Homeowners Need a Private Pre-Foreclosure Appraisal
Securing a private appraisal isn’t just about knowing a number; it’s about arming yourself with a “Defense Value” for legal proceedings. In Florida’s judicial system, a homeowner has 20 days to file a written response after being served with a foreclosure lawsuit. Having a certified report ready allows your legal counsel to present an objective baseline for the property value in foreclosure Florida courts require during mediation. This data is particularly vital if the lender seeks a deficiency judgment. By proving the home’s true worth, you can potentially limit your personal financial liability for the remaining balance owed to the bank.
Accurate data also shifts the power dynamic during short sale negotiations. Lenders often rely on their own internal valuations, such as Broker Price Opinions, which may be skewed toward a quick liquidation. A private pre-foreclosure appraisal provides the granular evidence needed to show why a specific offer is fair and should be accepted. This transparency helps avoid the 10-day objection period following a foreclosure sale, as it allows you to resolve the debt through a negotiated settlement before the property reaches the auction block.
Equity Protection Strategies
A certified valuation helps you determine the most logical exit strategy. If the report reveals significant remaining equity, you might choose to bypass the distressed sale route entirely. In this scenario, you can opt for a traditional sale to capture that cash before the lender completes the judicial process. This knowledge is essential when deciding between a deed-in-lieu of foreclosure or a short sale. Confidentiality is a cornerstone of this service. Professional. Discrete. Thorough. A private appraiser works for you, ensuring your financial position remains private while you weigh your options.
Working with Attorneys and Real Estate Professionals
Your legal team needs more than just your opinion of your home’s worth; they need a document that commands respect in a legal context. Providing a certified valuation allows your attorney to challenge low-ball auction prices or negotiate better settlement terms. Similarly, if you decide to list the property, this data helps your real estate professional set a realistic “quick sale” price that still protects your interests. For those who choose this path, our Pre-Listing Appraisal service provides the market clarity needed for a successful transaction. To protect your equity today, request a confidential pre-foreclosure appraisal from our methodical team.
Navigating the Florida Foreclosure Process with Meridian Property Appraisers Inc.
Managing the legal and financial complexities of a distressed sale requires more than just a general estimate of worth. It requires a partner who understands that data is your strongest ally. Meridian Property Appraisers Inc. provides the technical expertise required to establish the property value in foreclosure Florida homeowners need for a successful resolution. We don’t just provide a report; we offer a methodical defense of your equity through rigorous analysis. Precision. Integrity. Discretion. These core values guide our work, ensuring that your sensitive financial situation is handled with the highest level of professional conduct.
Our workflow mirrors the precision required by Florida courts. From the initial data collection phase to the final reconciliation of value, every step is documented with scrutiny. This methodical approach ensures that when you present your appraisal to a lender or judge, it carries the weight of a professional, certified valuation. We take the time to explain the underlying process, ensuring you feel informed and in control of your financial destiny.
Local Expertise Across the Sunshine State
National valuation firms often rely on automated models or data aggregators that miss the subtle shifts in local neighborhoods. Our team possesses deep knowledge of the Tampa, Saint Petersburg, Orlando, Miami, and Fort Lauderdale markets, where regional nuances significantly impact value. We also serve the growing communities of Clearwater, Largo, Pinellas Park, and Seminole, ensuring that homeowners in these regions have access to the same level of granular data as those in the major metropolitan hubs.
This local insight is essential to understand the property value in foreclosure Florida residents must prove to protect their equity. We understand how local inventory levels and specific Florida regulations influence your home’s worth. We’re committed to providing the clarity you need during stressful life transitions, acting as a stable pillar of expertise in a fluctuating market.
Taking the Next Step
The process of securing an accurate valuation is designed to be efficient and logical. It begins with a confidential inquiry where we identify your specific needs, whether you’re preparing for a short sale or a court-ordered mediation. During the property inspection, our certified appraisers conduct a thorough review of the home’s condition, taking the time to document the “As-Is” state that banks often overlook. This scrutiny ensures the final report is both comprehensive and defensible in a Florida courtroom.
You’ll receive a detailed document that serves as a professional walkthrough of your home’s market position, allowing you to negotiate from a place of strength. You don’t have to face the judicial timeline alone or rely on the bank’s biased figures. To protect your financial future with data-driven insights, you can Schedule a Confidential Pre-Foreclosure Appraisal today.
Secure Your Financial Future with Accurate Data
Protecting your home’s worth during a judicial process requires moving beyond guesswork. You now understand how the distinction between fair market value and liquidation value defines your negotiation leverage. By identifying the specific physical and market factors that influence your appraisal, you can take proactive steps to preserve your equity before an auction occurs. Determining the true property value in foreclosure Florida homeowners face requires a methodical, detail-oriented approach that prioritizes your financial interests over a lender’s recovery targets.
Meridian Property Appraisers Inc. offers the quiet competence and technical precision needed to navigate these transitions. Our certified Florida appraisers provide a discreet and professional service, backed by years of expert witness experience in legal and financial settlements. We focus on providing peace of mind through expertise, ensuring you have the data-driven proof required to negotiate a short sale or defend your equity in court. Precise. Objective. Decisive. You don’t have to navigate this complex timeline without a trusted advisor by your side.
Protect Your Equity with a Confidential Pre-Foreclosure Appraisal
Taking control of your valuation is the first step toward a stable resolution. You have the tools to protect your legacy and find a clear path forward.
Frequently Asked Questions
Does foreclosure automatically lower my property value in Florida?
Foreclosure doesn’t inherently change the physical property value in foreclosure Florida homeowners possess, but it shifts the valuation perspective from Fair Market Value to Liquidation Value. Lenders focus on a quick recovery of funds, which often results in a distress discount. While your home’s intrinsic worth remains, the price it fetches in a forced sale is usually lower than in a traditional market transaction.
How is property value determined in a Florida judicial foreclosure?
In Florida, a judicial state, value is determined through court-supervised processes. Lenders typically order a Broker Price Opinion or a full appraisal to set a minimum bid for the foreclosure auction. These valuations are used by the court to decide if a sale was fair and to calculate potential deficiency judgments. Having your own certified appraisal ensures the court sees an objective, data-driven figure.
Can I challenge the bank’s appraisal of my home?
You can absolutely challenge a lender’s valuation by presenting an independent, certified appraisal report. Bank-ordered assessments often overlook interior upgrades or use inappropriate comps that don’t reflect your home’s unique state. A private appraiser provides a detailed rebuttal, ensuring that the 20-day response period to a foreclosure lawsuit includes accurate data to protect your equity during mediation or court hearings.
What is the difference between a pre-foreclosure appraisal and a standard one?
A pre-foreclosure appraisal specifically addresses the as-is condition and the urgency of the sale. While a standard appraisal assumes a typical marketing time, this specialized version often includes liquidation and disposition values. It accounts for the 120-day delinquency period and the specific judicial timelines in Florida. This detail is essential for homeowners who need to negotiate short sales or deed-in-lieu agreements with their lenders.
Will a foreclosure in my neighborhood affect my home’s value?
Nearby foreclosures can negatively impact your home’s value by increasing the local supply of distressed properties. In the first half of 2026, Florida’s foreclosure rate was 0.27%, the highest in the nation. When several homes in your immediate area are in foreclosure, they become the primary comparables for appraisers. This saturation can drag down the property value in foreclosure Florida residents see in their specific neighborhoods.
How much equity do I need to avoid foreclosure through a sale?
To avoid foreclosure through a sale, you generally need enough equity to cover the mortgage balance, late fees, and seller closing costs. In Florida, closing costs typically range between 6% and 10% of the sale price. With the median home price in 2026 between $386,333 and $420,000, having at least 15% to 20% equity provides a safe cushion to pay off the lender and move forward.
Is a pre-foreclosure appraisal confidential?
A private pre-foreclosure appraisal is completely confidential. Unlike a lender-ordered assessment, this report belongs to you and is not shared with the bank or the court system without your permission. This allows you to assess your financial options, such as a quick sale or refinance, with total privacy. Professional appraisers prioritize discretion to give you a clear, unpressured view of your home’s worth.
How long is a foreclosure appraisal valid in the 2026 Florida market?
In the 2026 Florida market, an appraisal is typically considered valid for 90 days. Because the market is currently in a healthy rebalancing phase with a modest 2.8% annual appreciation, values are more stable than in previous years. However, if significant market shifts occur or if the property’s condition changes, a new assessment may be required to ensure the data remains defensible in legal or financial negotiations.


